For minibus & coach instructors

MTD for Income Tax for minibus & coach instructors.

D1 and D category training, a specialist vehicle, a mix of corporate and individual pupils and lumpy course income. Here's how Making Tax Digital for Income Tax applies to minibus and coach instructors, and when it starts.

When does it start for me?

For many, April 2027 is the date to watch.

MTD for Income Tax phases in by gross income before expenses. Course fees and corporate training can build a solid gross income across the year.

£50,000
Already live, from April 2026
Your likely date
£30,000
In scope from April 2027
£20,000
In scope from April 2028
Lumpy by nature

Uneven quarters are no problem.

Course work bunches into some quarters more than others. Quarterly updates report each quarter as it happens, and the year reconciles at your final declaration, so an uneven pattern is nothing to worry about.

What records you need →
What's changing

Digital records, four quarterly updates, one final declaration.

When you're in scope, your annual Self Assessment return is replaced by four short quarterly updates and a year-end final declaration, all through recognised software.

What to keep digital

  • Course and corporate training income
  • The training vehicle, as a major asset
  • Fuel and running costs
  • DVSA and registration fees
  • Insurance and maintenance
  • Premises or admin costs

Record each course and invoice so your quarterly figures reflect the work you actually did.

  • Training vehicle Major asset, claimed by method
  • Course income Lumpy, reconciled at year-end
  • Corporate and individual Both in one update
The training detail

The bits specific to D1 and D training.

The training vehicle

A specialist minibus or coach is a major asset. Record it correctly for capital allowances or deduction.

Lumpy course income

Courses bunch into some quarters. Quarterly updates handle it, reconciled at your final declaration.

Corporate and individual

Invoiced corporate work and individual course fees all sit in one set of records.

DVSA and insurance

DVSA fees and specialist insurance are deductible. Keep them recorded so nothing is missed.

Why Clear Books

Courses and the vehicle, kept clear.

Lumpy course income and a specialist vehicle need tidy records. Clear Books keeps them together and gives HMRC exactly what MTD needs, whenever you're in scope.
  • Record course and corporate income
  • Record the training vehicle correctly
  • Keep DVSA fees and insurance logged
  • See your gross income against the thresholds
  • Send HMRC-compliant quarterly updates in minutes
  • Free plan available, no timer
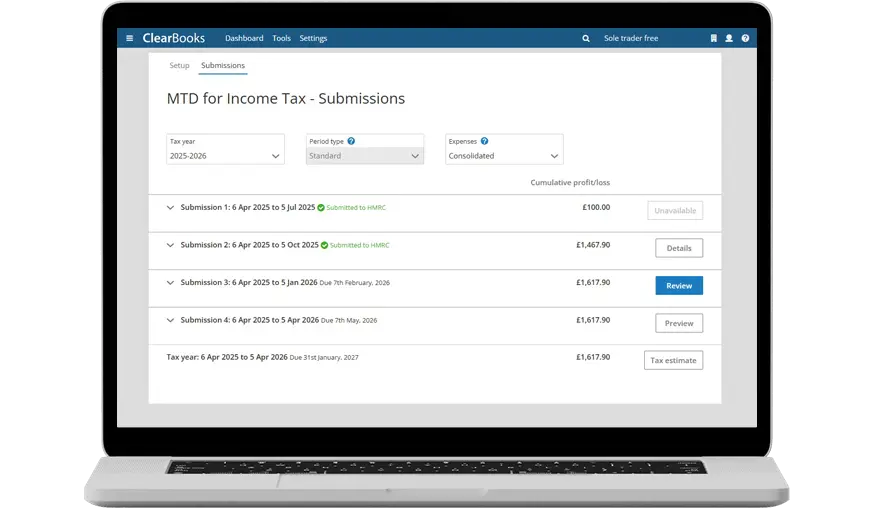
The Clear Books MTD for Income Tax submissions screen showing four quarterly updates submitted to HMRC
Q1 update submitted
HMRC recognised
Common questions

Minibus & coach instructor MTD FAQ.

When does MTD for Income Tax start for minibus and coach instructors?
The key date for many is April 2027, at £30,000 of gross income. Over £50,000 it applies now, and from April 2028 it drops to £20,000.
How is my training vehicle treated?
The specialist minibus or coach is a major asset, usually claimed through capital allowances if bought, or deductible if leased. Fuel and running costs are recorded separately.
How does lumpy course income work under quarterly reporting?
Courses can bunch into some quarters. Each quarterly update reflects that quarter, and your final declaration reconciles the whole year, so an uneven pattern is no problem.
I train corporate and individual pupils, does that change anything?
No. Corporate training is usually invoiced while individuals may pay per course, but it's all self-employed income in one set of records.
What else can I claim?
Typical costs include the training vehicle and fuel, DVSA and registration fees, insurance, and any premises or admin costs.
Free for self-employed instructors

Know where you stand before the deadline.

Record courses and the vehicle as you go, watch your gross against the thresholds, and be ready to submit when your wave lands.