Subscription and app income, platform fees, digital products and clients around the world, all with no premises. Here's how Making Tax Digital for Income Tax applies to online coaches, and when it starts.
MTD for Income Tax phases in by gross income before expenses. Your gross income is the full amount clients pay, before the platform takes its cut.
The threshold looks at the gross amount clients pay, not what lands in your account after the platform's cut. Recording your gross income and the fees separately keeps your figures accurate and your tax based on the net you keep.
When you're in scope, your annual Self Assessment return is replaced by four short quarterly updates and a year-end final declaration, all through recognised software.
Your processor statements are ready-made records; bring them in so your gross income reconciles cleanly.
Recurring plan and app income is steady. Bring in your processor statements so it reconciles to what you were paid.
Fees the platform or processor takes are deductible. Record your gross and the fees so you're taxed on the net.
Income from abroad is still yours to report. Record the payment and any conversion or fees as part of it.
Filming kit, software and a share of home and broadband are deductible. Keep them recorded so nothing is missed.
When platforms take a cut before you're paid, the margin needs to be clear. Clear Books keeps gross income and fees matched and gives HMRC exactly what MTD needs.
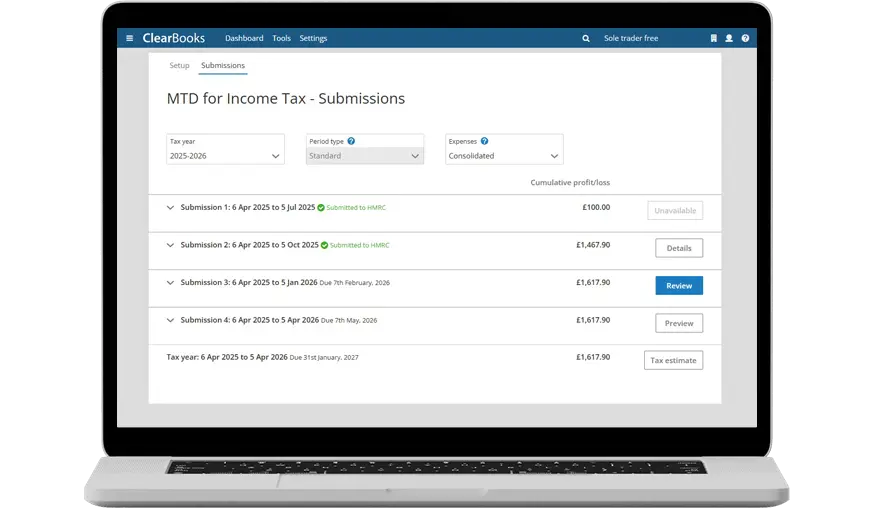
Bring in your income and fees, watch your gross against the thresholds, and be ready to submit when your wave lands.
