For minibus & coach owner-drivers

MTD for Income Tax for minibus & coach owner-drivers.

A mix of school runs and private hire, PSV and O-licence costs, seasonal charter work and the vehicle as a major asset. Here's how Making Tax Digital for Income Tax applies to minibus and coach owner-drivers, and when it starts.

When does it start for me?

In scope now over £50k, from April 2027 over £30k.

MTD for Income Tax phases in by gross income before expenses. A busy mix of contracts and charters can reach the threshold, so it's worth knowing your wave.

Live now
£50,000
In scope from April 2026
Your likely date
£30,000
In scope from April 2027
£20,000
In scope from April 2028
Contracts and charters

Steady school runs, lumpy charters.

School contracts give you predictable, invoiced income, while charters are seasonal and lumpier. Both sit in one set of records, and recording the vehicle and licence costs keeps your profit clear.

What records you need →
What's changing

Digital records, four quarterly updates, one final declaration.

When you're in scope, your annual Self Assessment return is replaced by four short quarterly updates and a year-end final declaration, all through recognised software.

What to keep digital

  • School-contract and charter income
  • The coach or minibus, as a major asset
  • Fuel and running costs
  • O-licence and PSV costs
  • Insurance and maintenance
  • Cleaning and booking software

Record the vehicle and licence costs against your income so your profit is realistic.

  • The vehicle Major asset, claimed by method
  • O-licence Deductible compliance cost
  • Charters Seasonal, reconciled at year-end
The operator detail

The bits specific to running a coach or minibus.

The vehicle

A major asset, claimed through capital allowances or deducted if leased. Record it correctly for the right treatment.

O-licence and PSV

Operator licence, PSV and compliance costs are deductible. Keep them recorded so nothing is missed.

School contracts

Steady, invoiced income. Record each invoice and it totals into your quarterly update.

Seasonal charters

Charter work peaks in season. Quarterly updates report it as it happens, reconciled at year-end.

Why Clear Books

Contracts, charters and the vehicle.

Steady contracts and lumpy charters, plus a big vehicle to account for. Clear Books keeps it tidy and gives HMRC exactly what MTD needs, whenever you're in scope.
  • Record contract and charter income
  • Record the vehicle for the right treatment
  • Keep O-licence and PSV costs logged
  • See your gross income against the thresholds
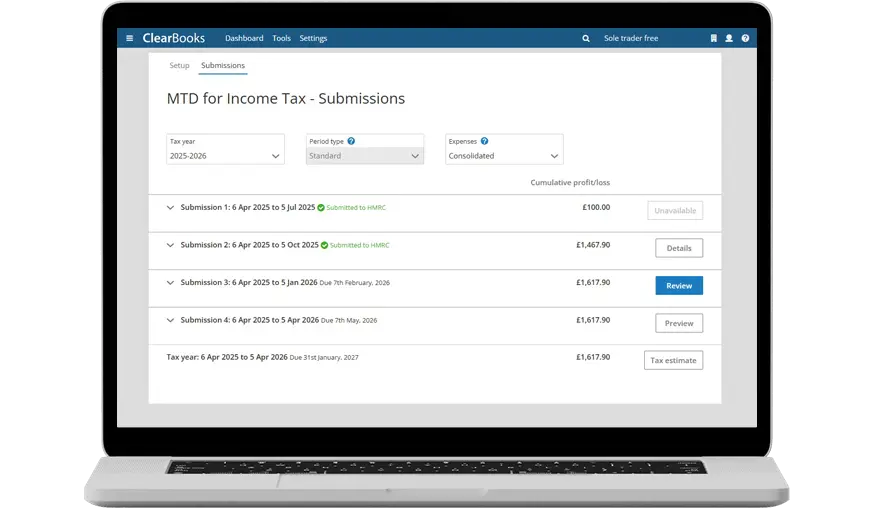
  • Send HMRC-compliant quarterly updates in minutes
  • Free plan available, no timer
The Clear Books MTD for Income Tax submissions screen showing four quarterly updates submitted to HMRC
Q1 update submitted
HMRC recognised
Common questions

Minibus & coach owner-driver MTD FAQ.

When does MTD for Income Tax start for minibus and coach owner-drivers?
If your gross income is over £50,000 it applies now, from 6 April 2026. Between £30,000 and £50,000, your start date is April 2027, and from April 2028 it drops to £20,000.
How is my coach or minibus treated?
A major asset, usually claimed through capital allowances if bought, or deductible if leased or financed. Fuel and running costs are recorded separately.
Can I claim PSV and O-licence costs?
Yes. Operator licence, PSV-related costs, insurance and maintenance are deductible business expenses.
How do school runs and charters sit together?
School contracts are steady, invoiced income, while charters are lumpier and seasonal. Both sit in one set of records and total into a single quarterly update.
What else can I claim?
Typical costs include the vehicle and fuel, O-licence and PSV costs, insurance, maintenance, cleaning and any dispatch or booking software.
Free for sole trader operators

Know where you stand before the deadline.

Record contracts, charters and the vehicle as you go, watch your gross against the thresholds, and be ready to submit when your wave lands.